


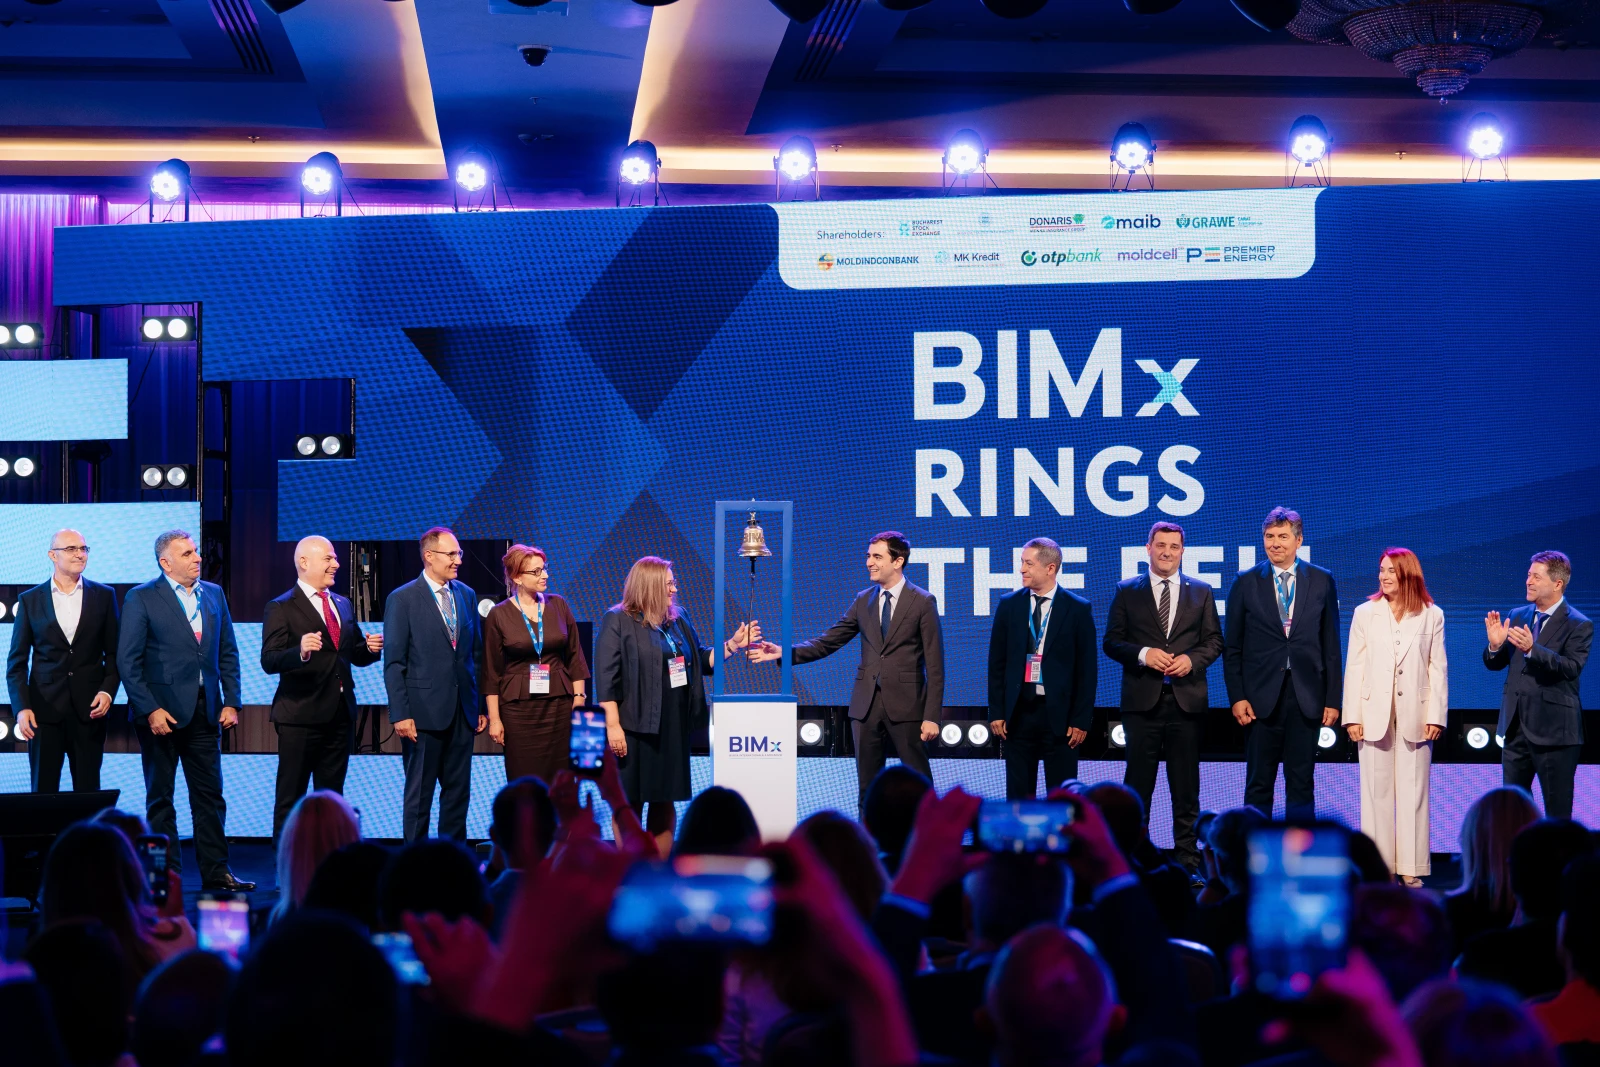
At the opening of Moldova Business Week 2026, it was announced that the Bursa Internațională a Moldovei (BIMx) had entered the final phase of its launch: Starting September 28, brokers began connecting to the trading system and issuers began registering, with the first offering on the new platform expected by the end of the year. What makes this event unique is that the country already has a stock exchange: the Bursa de Valori a Moldovei (BVM) has been operating since 1995.
Now, two stock exchanges will operate in this small economy. And this is happening in a market where the problem has long been not so much a lack of infrastructure as a shortage of securities, investors, and liquidity.
According to data from the National Commission for the Financial Market (NCFM), in the first half of 2026, the volume of registered securities issuances grew by 71.8% and reached 733.76 million lei. However, 81.8% of this amount (600.28 million lei) came from just four corporate bond issues, all four of which were issued by a single issuer—maib. Meanwhile, the total number of issues fell from 28 to 17.
The secondary market is even more telling. Over the first half of the year, transactions totaling 756.16 million lei took place there, but only 62.9 million lei occurred directly on the regulated market, while another 3.52 million lei took place on the Multilateral Trading Facility (MTF), an organized platform where orders from multiple buyers and sellers are matched according to established rules. The remaining 689.74 million lei—or more than 91% of total turnover—came from transactions outside the regulated market and the MTF.
Thus, in a situation where the existing exchange infrastructure accounts for less than 10% of secondary trading volume, another trading venue is emerging in the country. The BVM, however, is not going anywhere. It continues to operate as a regulated market operator and manages its own MTF, both of which are supervised by the National Commission for the Financial Market (NCFM). These platforms handle shares, corporate bonds, and municipal bonds. BIMx is not a replacement for the previously absent infrastructure, but rather an attempt to build a new capital market model in parallel.
At the same time, the weakness of the previous model is not explained solely by the structure of the exchange itself. Over the past 20 years, the pool of potential issuers has also shrunk significantly. In the mid-2000s, there were more than 3,000 joint-stock companies in Moldova, and by the end of 2006, the regulator had recorded over 3,700 companies that had registered initial public offerings. A significant portion of these joint-stock companies emerged as a result of mass privatization and were not fully operational even at that time.
Since then, the number of joint-stock companies has been steadily declining: companies are being liquidated or converted into limited liability companies. Between 2023 and 2025 alone, 341 companies were removed from the Register of Securities Issuers: 257 due to liquidation and 84 as a result of reorganization. According to an assessment by the National Commission for Financial Market (NCFM) conducted in 2025, approximately 600 joint-stock companies were actively filing reports—several times fewer than two decades ago.
The reason is not solely related to reporting, although corporate procedures, disclosure requirements, and regulatory obligations are significantly more complex for joint-stock companies than for limited liability companies (LLCs). The majority of Moldovan private businesses are characterized by ownership concentrated in a single owner or a small group of owners. To go public, they must not only disclose more information and respect the rights of minority shareholders, but also be prepared to allow outside investors to participate in the company's management. For businesses that do not intend to relinquish control, the advantages of this model do not always outweigh the additional obligations.
As a result, companies more often opt for bank loans rather than raising capital through the sale of shares. In 2025, the BVM's secondary market statistics listed only 13 issuers: five on the regulated market and eight on the MTF.
Will BIMx be able to change anything? The new exchange's authorized capital is 29.475 million lei. The Bucharest Stock Exchange became the largest shareholder with a 26.67% stake, while the state owns 20%. Other shareholders include Donaris VIG, maib, Grawe Carat Asigurari, Moldindconbank, MK Kredit, OTP Bank Moldova, Moldcell, and Premier Energy. BIMx will use the Bucharest Stock Exchange's ARENA technology platform.
The project's scope extends far beyond technological modernization. The new platform is intended to provide companies with an alternative to bank lending, attract investors, and expand financing opportunities through stocks and bonds. In essence, this is an attempt to transform the established model of capital flow in the Moldovan economy.
Today, banks remain the primary intermediary between savings and business. A company that needs money for development typically applies for a loan, while a citizen with disposable income places those funds in a deposit account. The stock market offers a more direct structure: a company issues stocks or bonds and receives funds directly from investors.
It is telling that the banks themselves are participating in the creation of a potential competitor to bank financing. maib owns 10% of BIMx, Moldindconbank owns 6.67%, and OTP Bank Moldova owns 3.33%. Together, this amounts to 20% of the new exchange's capital. For banks, this does not necessarily mean a loss of business: part of traditional lending can be replaced by brokerage services, bond placements, underwriting, and other investment products.
The main difference between BIMx and the existing exchange is its close ties to Bucharest. The Bucharest Stock Exchange is the largest shareholder and provides the technological platform; however, BIMx remains a Moldovan operator under the supervision of the National Commission for the Financial Market (NCFM), and settlements must go through the Unified Central Securities Depository, which is supervised by the National Bank of Moldova.
The use of Romanian technology does not imply a merger of the two markets and does not grant Moldovan investors automatic access to securities traded in Bucharest. But the direction is clear: the new platform is being created with a view toward deeper integration of Moldova into the European capital market.
Moldova needs foreign capital, and facilitating access for international investors to local companies could expand their financing options. But financial integration works both ways: as barriers are removed, it may also become easier for Moldovan capital to seek investment opportunities outside the country.
Therefore, it is not only important how much foreign capital the new exchange will be able to attract. It is equally important whether Moldova will be able to offer its own investors attractive enough assets to keep their capital in the country.
And a single new exchange is not enough to achieve this. BIMx faces the challenge of solving a problem that the Moldovan stock market has failed to resolve over the past three decades: convincing businesses to disclose more information, issue securities, and allow external investors access to capital—while encouraging investors with disposable income to purchase these securities.
Ultimately, BIMx's success will be measured not by its first listing or the number of connected brokers, but by the number of new issuers, the amount of capital they raise, and the emergence of a liquid market. Otherwise, Moldova will have two stock exchanges but still a stock market that is far too small. // 30.09.2026 — InfoMarket.